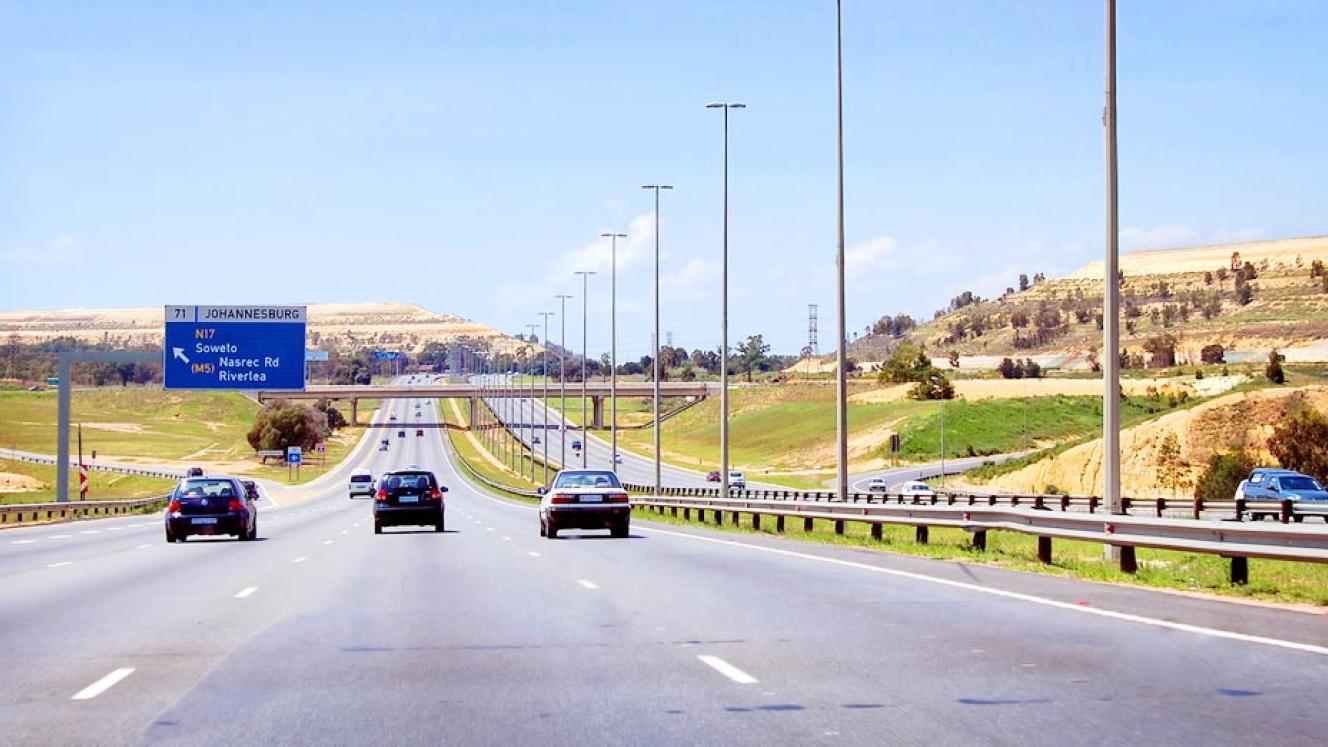
Improvements in electricity supply will not translate fully into higher production and exports unless rail, port and other infrastructure constraints are addressed, according to PwC’s latest South Africa Economic Outlook: Q3 2026 report.
Progress in one part of the supply chain can expose weaknesses elsewhere, preventing businesses from turning improved operating conditions into investment, sales and employment, the report warns.
Its Growth Conversion Map examines how constraints interact across electricity, freight and water systems, highlighting the need to identify the specific problems affecting individual sites, suppliers, corridors and customer markets.
For mining companies, more reliable electricity and water can support higher production, but insufficient rail and port capacity can still prevent additional output from reaching export markets.
Manufacturing and agriculture face similar challenges. Reliable utilities need to be supported by functioning processing facilities, cold chains and transport routes before increased production can translate into sales, according to the report.
“The challenge is no longer simply about whether infrastructure is improving at a national level. Businesses experience infrastructure through specific networks, corridors, utilities and sites,” said PwC South Africa associate director and lead economist for sustainability, Dirk Mostert.
“Progress in one area can increase economic potential, but another weak link can still prevent that potential from translating into economic activity.”
Rail performance illustrates the scale of the challenge. PwC cites freight volumes of 160.1 million tonnes in 2024/25, leaving a gap of 89.9 million tonnes against the government’s target of 250 million tonnes by the end of 2030.
More recent Transnet results show that rail volumes increased by 4.9% to 167.9 million tonnes in 2025/26. While this represents further improvement, substantial growth is still required to reach the target.
The gap to the target measures the additional throughput required; it does not represent a quantified loss of exports.
Businesses had adapted to unreliable infrastructure by absorbing additional operating costs and building buffers, said PwC chief economist and Africa sustainability leader Lullu Krugel. Stronger growth, however, requires investment in productivity rather than simply protecting existing operations.
“South Africa’s economy continues to demonstrate resilience, but stronger growth will require us to convert improving conditions into productive economic activity. We are seeing meaningful progress in areas that have constrained the economy for several years,” Krugel said.
“The opportunity now is to build on that progress and ensure it translates into stronger investment, production and employment.”
PwC forecasts real GDP growth of 1.1% in 2026 and 1.3% in 2027, with elevated inflation and interest rates continuing to weigh on economic activity.
GDP contracted by 0.2% quarter on quarter in the second quarter of 2026, although output remained 0.9% higher than a year earlier. The figures point to an uneven recovery, with industrial activity and business confidence still under pressure, according to the report.
The effectiveness of structural reforms will depend on whether national improvements translate into reliable services and infrastructure where businesses operate, PwC argues.
“If South Africa can strengthen the links between reform, implementation and the operating environment, there is an opportunity to translate the progress already achieved into stronger investment, productivity and jobs,” Krugel said.