Original equipment manufacturers (OEMs) could find it easier to substantiate customs-duty rebate claims involving imported component content destroyed under customs supervision, under amendments proposed by the International Trade Administration Commission (ITAC).
Published in Government Gazette No. 55525 on October 9, Notice 4188 proposes amendments to the notes under Rebate Item 412.00 of Schedule No. 4 to the Customs and Excise Act.
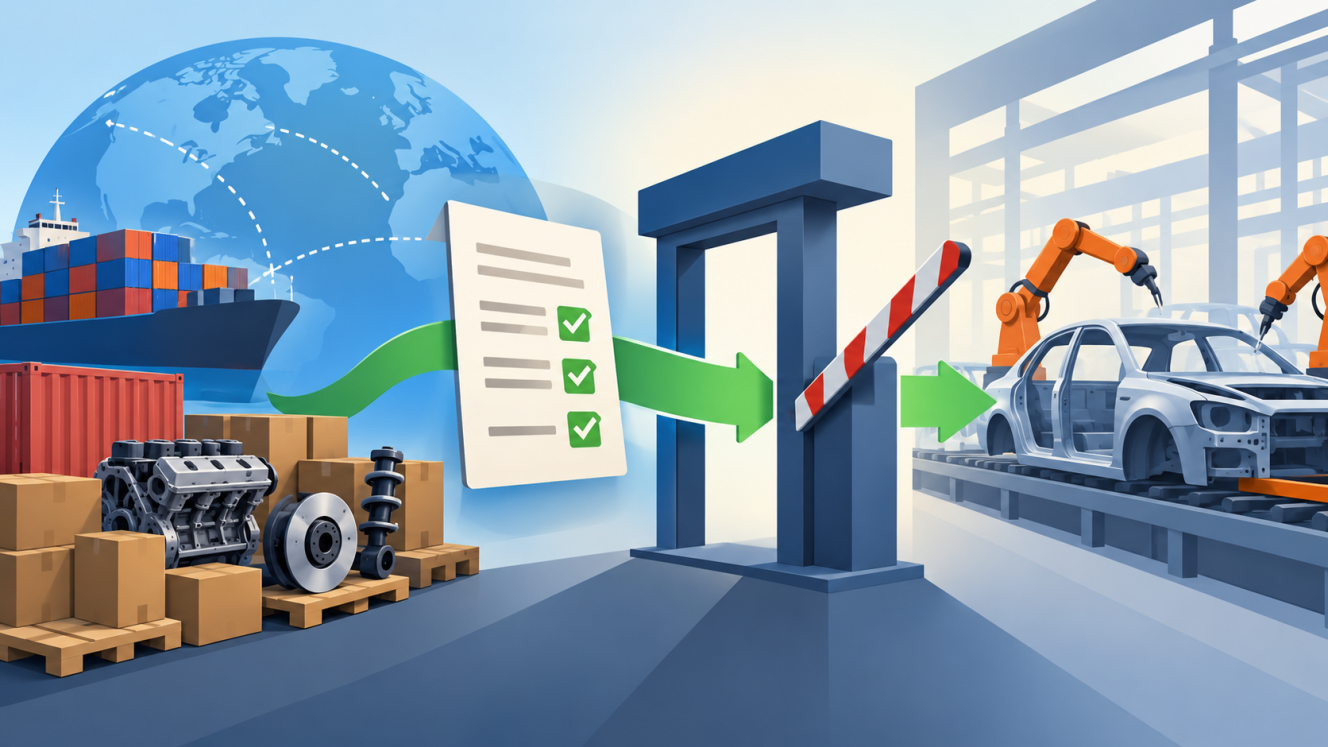
The proposal addresses a documentation problem affecting OEMs that purchase imported components from local suppliers rather than importing the goods themselves.
According to ITAC, manufacturers struggle to obtain the relevant bills of entry because their suppliers hold the import records. These documents contain confidential information about suppliers’ import transactions, which they may be unwilling to share with their OEM customers.
This creates a practical compliance barrier. Although the imported component content is ultimately destroyed under customs supervision, OEMs may be unable to substantiate its imported value sufficiently to claim the available customs-duty rebate, ITAC said.
Under the current provisions, OEMs are generally required to submit the relevant bills of entry, invoices and supporting import documentation when applying for the rebate.
The proposed amendment would allow Form C2 to be used as an alternative supporting document in these circumstances.
According to the notice, the South African Revenue Service (Sars) recognises this use of Form C2 in its initial assessment. Sars indicated that the amendment would enable OEMs to use an existing reporting mechanism rather than introduce an entirely new compliance requirement.
The proposal could therefore ease the documentation burden on affected manufacturers when suppliers are unwilling to disclose their import records. It remains subject to public consultation.